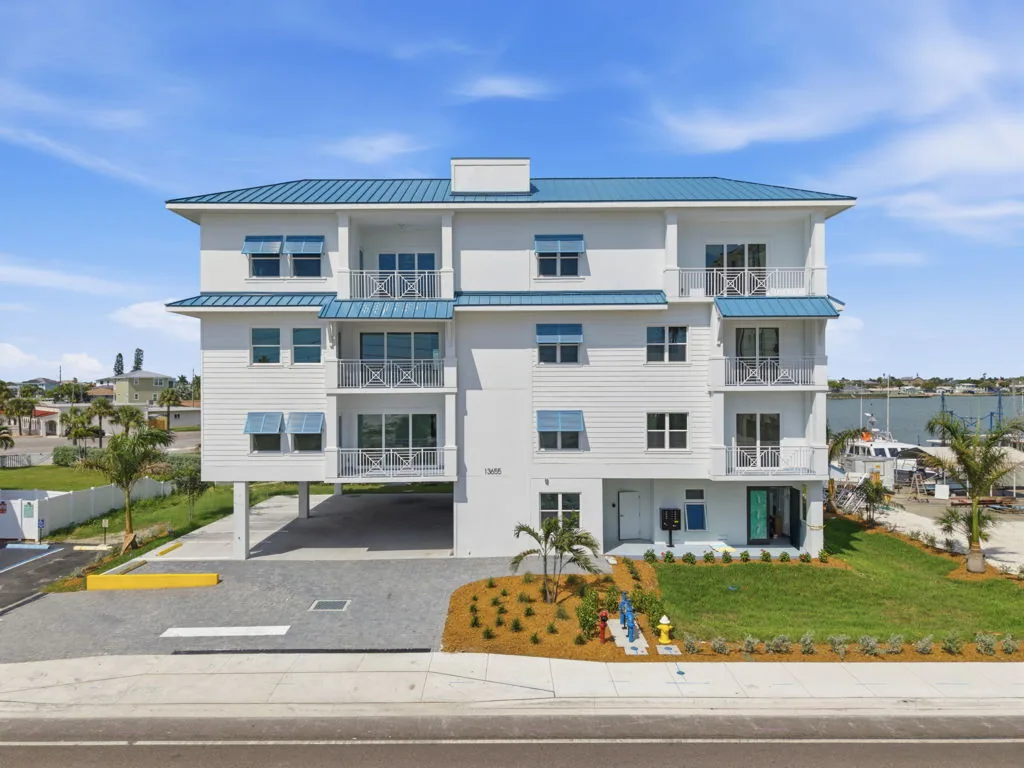
DSCR Loans for Florida Vacation Rentals: How They Work
Last reviewed · Smart Coastal Assets
The short answer
A DSCR loan is an investment-property mortgage that qualifies you mainly on the property's rental income instead of your personal income. The lender divides the property's expected rental income by its monthly debt payment (principal, interest, taxes, insurance and association dues). A ratio of 1.0 means the rent exactly covers the payment; many lenders look for 1.0 to 1.25 or higher.
How DSCR is calculated
DSCR = rental income ÷ PITIA (principal, interest, taxes, insurance and association dues). For example, if a residence is expected to rent for $12,000 per month and the full monthly payment is $10,000, the DSCR is 1.2.
For vacation rentals, lenders may use short-term-rental market data or an appraiser's rent estimate rather than a long-term lease.
Typical features
- No personal income verification (tax returns, W-2s) in most programs; credit and reserves still matter.
- Larger down payments than owner-occupied loans are common; many programs start around 20–25%.
- Rates are usually higher than conventional mortgages.
- Loans are typically made to individuals or LLCs for investment use.
Smart Coastal Assets residences with DSCR financing
| Residence | Financing options | Total down payment |
|---|---|---|
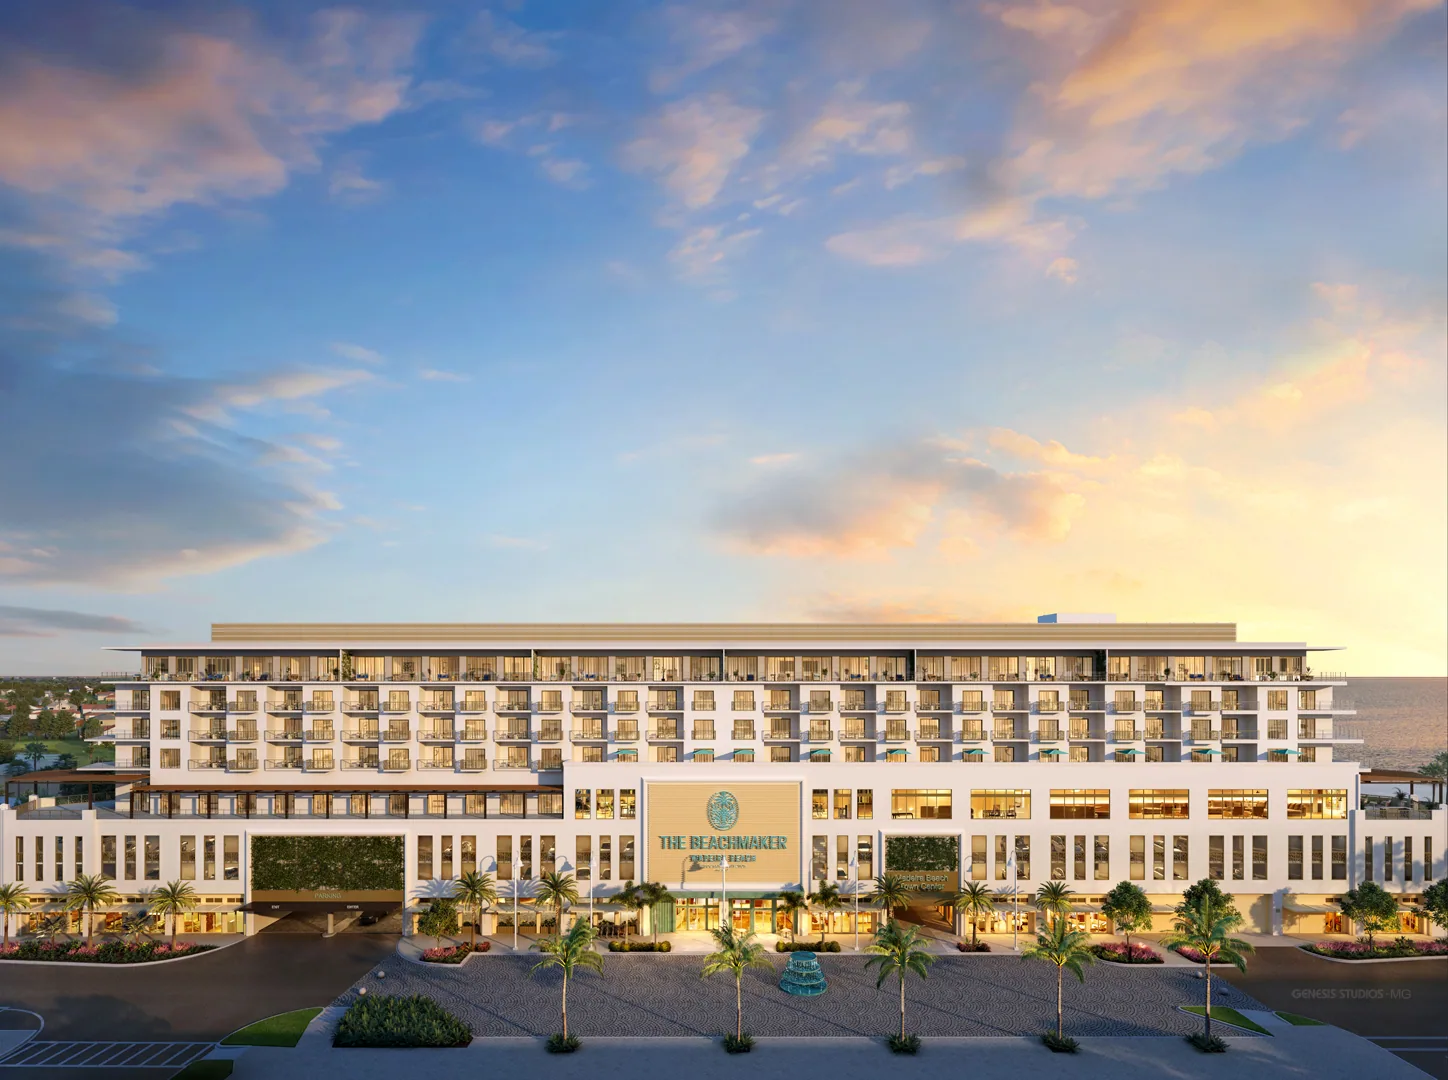
| The Beachmaker Resort | Cash, conventional and DSCR financing (subject to approval) | 20% placed in escrow for select Founders Club residences |
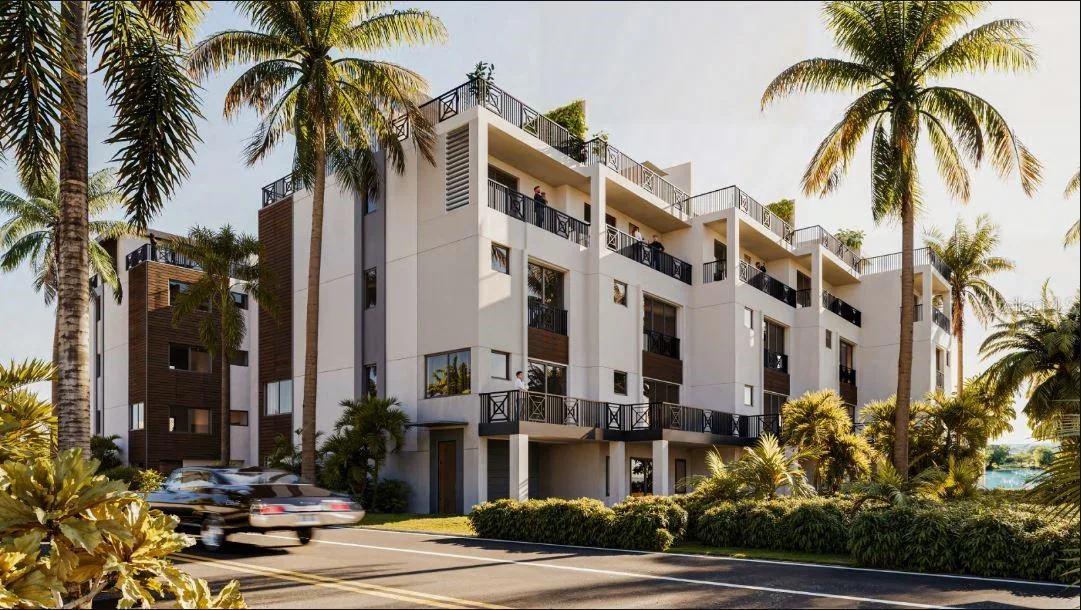
| Sapphire Shores | Cash, conventional, second-home or DSCR financing | 20% |
| Capri Townhomes | Cash, conventional or DSCR financing (subject to lender approval) | 20% |
| The Residences | Cash, conventional or DSCR financing (subject to underwriting) | 10% |
| Coastal Elegance at Snug Harbor | Cash, conventional, DSCR or investment loans (subject to lender approval) | 20% |
Frequently asked questions
What does DSCR stand for?
Debt service coverage ratio: the property's rental income divided by its total monthly debt payment (principal, interest, taxes, insurance and association dues).
Can I use a DSCR loan for a short-term rental?
Many DSCR lenders accept short-term rentals and use market data for nightly rental income. Property rules matter: the residence must permit the rental use the lender is underwriting.
Sources
Loan terms vary by lender and borrower. All financing is subject to lender approval.
Have a question about a specific residence?
Request Information